Orbital Gridlock: Launch Diversity Fails to Match Record Capacity
Despite a historic surge in launch activity, satellite operators face a critical shortage of mission-specific orbital access. The industry is grappling with a shift where raw capacity no longer satisfies the demand for flexible, diverse delivery to space.
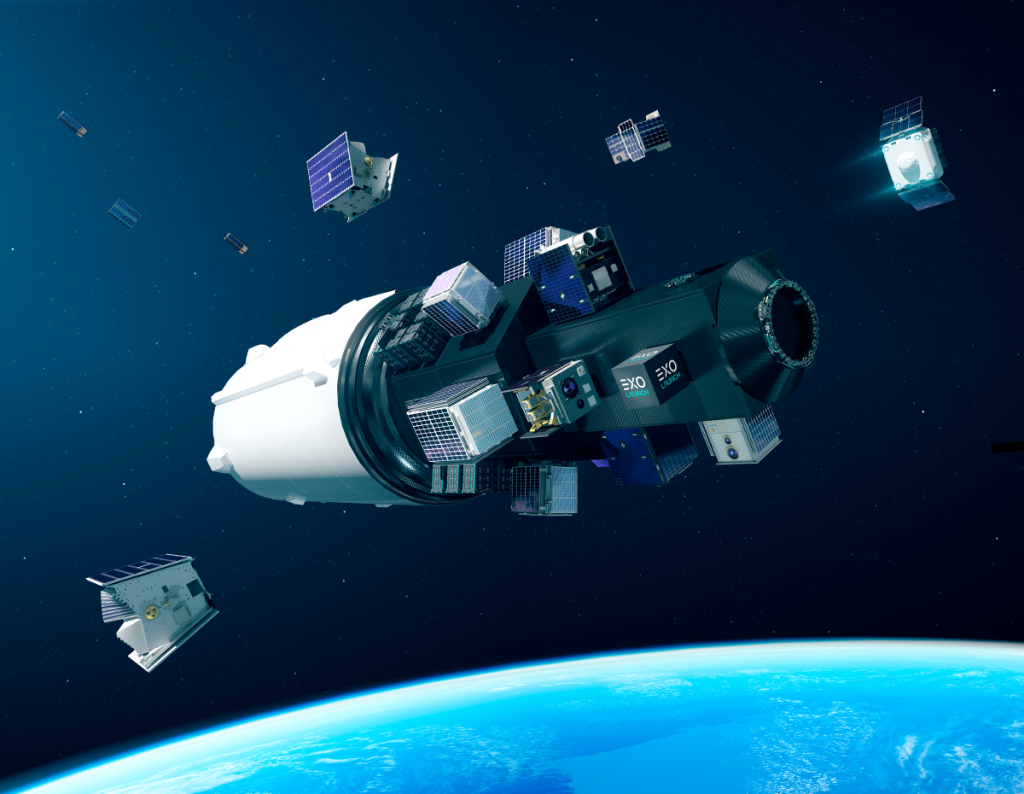
DATA OVERLOAD: THE CAPACITY PARADOX
Global launch activity has achieved record-breaking frequency, yet the orbital sector is facing a strategic bottleneck. According to SpaceNews, satellite operators are struggling with a severe lack of flexibility. While the raw number of rockets entering orbit is rising, the diversity of vehicles and destinations has contracted significantly compared to a decade ago.
LOGISTICAL CONSTRAINTS
FAA data indicates 187 licensed launches in fiscal year 2026, nearly doubling figures from 2016. However, this volume is concentrated among a few dominant providers. Robert Sproles, CEO of Berlin-based Exolaunch, warns that the demand curve is vastly outstripping the supply curve. The issue is no longer just getting into space; it is reaching the correct orbit at the required time.
"We need to recognize what types of launches are best for what types of missions," Sproles noted, emphasizing that the current market lacks the variety seen in 2016 due to geopolitical shifts and post-pandemic supply chain disruptions. The market is currently split between high-volume rideshare vehicles like SpaceX’s Falcon 9 and precision small-sat launchers like Rocket Lab’s Electron.
THE TRILLION-DOLLAR TARGET
With the space economy projected by Novaspace to reach $1 trillion by 2034, a monolithic launch model is no longer sustainable. While rideshare missions offer lower costs for flexible payloads, increasing mission complexity requires dedicated and "shared launch" alternatives. The industry must move beyond haphazard piggybacking toward intentional, customized deployment strategies to ensure the $626 billion space economy continues its 5.5% annual growth trajectory.